If you have contemplated learning how to sell final expense insurance or how to become an insurance agent, there is no better time than now to learn the business.
My name is Drew Gurley and what you’ll find in this guide is a lot of information I have learned from my personal experience selling final expense out in the field, building insurance businesses, and learning from other mentors along the way.
Some of the most successful final expense agents came from completely unrelated industries, so don’t be afraid to change careers and learn about selling final expense insurance.
This is your opportunity to transition within the industry, change careers, or add a new service line to your agency.
Have you ever wondered what sales language top Final Expense Agents use?
FREE Top Producer Presentation
(FREE Download)
How to Sell Final Expense Insurance in 7 Steps
To sell final expense insurance, you need a life insurance license, carrier contracts, a reliable prospecting strategy, basic field underwriting knowledge, a repeatable sales presentation, and a system for tracking placement, persistency, chargebacks, and profitability.
The final expense business isn’t complicated, but that doesn’t mean it’s easy.
At a high level, becoming a successful final expense agent comes down to seven things:
01
03
04
05
06
07
The agents who succeed aren’t necessarily doing something revolutionary. They consistently execute a proven process.
What’s in this guide to selling final expense insurance and who is it for?
This guide will uncover the not-so-mysterious business of selling final expense insurance and how successful agencies build consistent production.
There’s something for everyone:
- If you’re new to final expense, you’ll understand how to get started.
- If you’re a seasoned vet, you’ll find ways to improve your sales process and lower your costs of acquisition.
- If you’re just getting started selling insurance, you’ll know quickly if final expense insurance is for you.
There are a lot of elements you need to consider before taking the plunge, and I’m going to show you how the business works step by step.
Let’s get started.
What is Final Expense Insurance?
Final expense insurance is life insurance designed primarily to help cover funeral costs and other expenses a family may face after someone dies. It is generally sold as lower-face-amount permanent life insurance, often using simplified underwriting.
The final expense market is still growing. According to the 2026 LIMRA–Life Insurers Council Final Expense Survey, 30 participating carriers reported $1.38 billion in new annualized premium in 2025, up 32% from 2024, and nearly 1.3 million policies issued. Independent distribution accounted for 75% of the policies reported.
Some smart guy coined the term “Final Expense” to describe low face amount life insurance which is sold primarily to seniors or retirees to address funeral planning. What a genius. I wish it was my idea! Final expense insurance is typically a lower face amount whole life policy. In the 2025 LIMRA–LIC survey, simplified-issue final expense policies had an average face amount of $15,344, while guaranteed-issue policies averaged $11,299. Here’s a quick look at the final expense sales process:
- Get your life insurance license (you can order your life license study materials here)
- Get contracted to sell final expense
- Start a lead campaign.
- You (new final expense agent) receive a lead card in the mail from a client interested in a $10,000-$15,000 policy to cover the cost of their funeral. Your goal is to sell them a $10,000 – $15,000 whole life insurance policy (final expense policy) to cover the final expenses the family will face upon their passing.
- You’ll likely set the client up on an automatic electronic funds transfer (EFT) from their bank account for their roughly $40-$60 per month premium, which is paid directly to the insurance company.
- The entire sale will take less than 90 minutes and you’ll walk out the door with a pending commission to hit your account in as little as 24 hours.
Many final expense products use simplified underwriting and do not require a traditional medical exam, although health questions, prescription history, database checks, age limits, and other underwriting requirements vary by carrier and product. Sounds easy, right? It can be. If you dedicate yourself to the growing senior market, final expense life insurance can be a great way to make money selling insurance.
What Are the Different Types of Final Expense Insurance Plans?
There are four types of policies you will sell out in the field or over the phone, all of which are based on the health of your prospect, which ultimately dictates how the death benefit is paid out. It’s important to clearly understand the difference so you are always giving your client the best options.
Level Final Expense Plans
Level plans will pay the full amount of the life insurance benefit starting immediately upon approval. For example, if you sell a level benefit policy for $12,000, the policy beneficiary will receive the full policy amount upon death of the insured, even if they die within the first week of the policy being active. Other types of final expense policies—detailed following this—have various waiting periods and alternative payment methods before the full amount of the policy is paid in the event of the death of the insured. Level plans are the most cost-effective type of final expense plans your clients can qualify for and, in most cases, pay the highest commissions.
Graded Final Expense Plans
Graded plans can be an option for clients with certain pre-existing health conditions who do not qualify for an immediate full death benefit.
Instead of paying the full natural-death benefit immediately, these policies generally limit the natural-death benefit during an initial period. The exact schedule varies by carrier and product, so never assume one company’s graded benefit works the same way as another.
Your job as the agent is to understand the contract, explain the limitation clearly, and determine whether another carrier can offer the client a stronger benefit.
Modified Final Expense Plans
Modified burial insurance plans are nearly identical to graded plans, except for the type of payout. Modified plans are used for pre-existing conditions that pose a higher risk for the insurance company, which results in a reduced payout schedule (using a $10,000 policy as the example):
- Year 1: Return of your premiums paid to date + 10% interest
- Year 2: Return of your premiums paid to date + 12% interest
- Year 3: 100% of the $10,000 payout
- Accidental death in any year pays 100% of the death benefit.
The important thing to remember about modified burial insurance plans is that it is worth shopping other insurance companies because you might be able to qualify for a graded plan, which would increase the payout to your client’s family and lower their costs.
Guaranteed Issue Final Expense Plans
Guaranteed issue final expense is designed for applicants who may not qualify for medically underwritten or simplified-issue coverage. These products generally do not require health questions or a medical exam, but they commonly include a limited or graded natural-death benefit during the early policy years.
That is why it is so important to have multiple companies as a final expense agent. A prospect who appears to need guaranteed issue may qualify for a stronger benefit with another carrier after you complete proper fact finding.
Do not memorize one generic guaranteed-issue payout schedule. Benefits, issue ages, face amounts, state availability, and limitations vary by carrier and can change. Always use the current carrier-approved product guide and policy language.
Understanding the Funeral Market
Another thing you need to do is stay updated on the funeral industry as a whole.
Understanding consumer trends will help you have a better conversation with your prospects because the way families plan and pay for funerals continues to change.
According to the National Funeral Directors Association, the U.S. cremation rate was projected to reach 63.4% in 2025 compared with a 31.6% burial rate. NFDA’s latest published national median figures show a funeral with viewing and burial at $8,300 and a funeral with cremation at $6,280.
Source: National Funeral Directors Association statistics
The lesson for an agent is simple: don’t assume every client needs the same face amount. Ask what they want the policy to accomplish, understand the type of final arrangements they expect, and help them select an amount they can reasonably afford.
The more you know about your industry and can communicate to your prospects during your conversations, the more they will see you as an expert in your field.
Final Expense Insurance Companies to Sell
Final expense life insurance products are somewhat of commodity, especially when you consider the total number of final expense companies in the market today. We get asked this question all the time and the response is almost always the same. Sell what is best for your customer. With as many final expense companies that are available, you should be able to pick any combination of 4 companies that will help you build a strong book of business while also doing what is best for your clients.
Best Final Expense Insurance Companies
We prefer the companies in bold.
| Company Name | ||||
|---|---|---|---|---|
| (Recommended) Mutual of Omaha | ||||
| (Recommended) Prosperity Life | ||||
| (Recommended) Royal Neighbors of America | ||||
| (Recommended) Transamerica | ||||
| (Recommended) American Continental | ||||
| (Recommended) Gerber Life | ||||
| (Recommended) Columbian Mutual Life | ||||
| AIG | ||||
| American Amicable Life Insurance Company of Texas | ||||
| American Home Life Insurance Company | ||||
| Americo Financial Life and Annuity Insurance Company | ||||
| Assurity Life Insurance Company | ||||
| Baltimore Life Insurance Company | ||||
| Equitable Life Insurance | ||||
| The Independent Order or Foresters | ||||
| Gleaner Life Insurance Company | ||||
| Great Western Insurance Company | ||||
| Kemper | ||||
| Liberty Final Expense | ||||
| Medico Insurance Company | ||||
| Nationwide | ||||
| New York Life Insurance Company | ||||
| Oxford Life Insurance Company | ||||
| Sentinel Security Final Expense Insurance | ||||
| Security National Final Expense Insurance | ||||
| Senior Life Insurance Company | ||||
| S. USA Life Insurance Company (Prosperity) | ||||
| Trinity Life Insurance Company | ||||
| United American insurance Company | ||||
| United Home Life | ||||
| United of Omaha Life Insurance Company |
How to Get Started as a Final Expense Insurance Agent
Getting started doesn’t need to be difficult, but you do need to do your homework and dedicate yourself to becoming an expert.
Get a Life Insurance License
The first thing you need to do is get licensed to sell life insurance. In order to get a life insurance license, you need to follow the state required guidelines. Some states require passing a moderated test and some require taking an in-person course. Here is a link you can use to start the process of getting your life insurance license. Once you’re licensed, you can follow the remaining steps in this detailed guide on how to sell final expense.
Get Your Life Insurance License Here
Don’t try to recruit
One of the ways agents make a lot of money selling final expense is by recruiting agents to their hierarchy. Most of the time they try recruiting too soon. You should learn the entire business on your own before you start trying to pitch the opportunity to other agents. If you start recruiting too early, you’ll get stuck with a bunch of bad agents who write and place bad business that ends up charging back. When it charges back and they can’t afford to pay it back, it will roll up to you. Are you prepared to cut a check for $1,000, $10,000, or $20,000? Become an expert on the business before you start trying to take financial responsibility for someone else.
Follow a System or a Proven Producer
If you are going independent, the organization above you matters. Redbird has a separate guide on how to choose a final expense FMO, including the questions I would ask before signing a contract.
There is a proven approach to selling final expense that works. Find someone or an FMO with real production experience and learn their process before trying to reinvent it.
Invest in Yourself
Final expense does not require the same capital investment as many traditional businesses, but that does not mean it is free to build.
You should expect to invest in licensing, contracting, technology, leads, training, transportation if you are selling in the field, and enough working capital to survive the normal ups and downs of commission income.
Investing in yourself is the difference maker and that is where a lot of agents fail. Take the time to invest in your business on a weekly basis.
Also, take some time to learn about the various products on the market your client will be exposed to. Become familiar with consumer-direct offers such as Colonial Penn life insurance products, AARP, Globe Life, and the other insurance offers your prospects receive through the mail and online.
This way you can speak intelligently about these products when a client brings them up.
Final Expense Commissions and Business Economics
How are final expense agents paid?
Final expense agents are generally paid a percentage of the policy premium according to the carrier’s compensation schedule. Independent agents may receive commissions directly from the carrier, and commissions may be paid as earned or partially advanced. Actual compensation varies by carrier, product, contract level, issue age, and distribution relationship.
Before you spend money on leads, it is important to understand how final expense commissions work, how carriers advance commissions, and how chargebacks can affect your cash flow.
What does street level commission mean?
Street level is industry shorthand for a carrier’s standard independent writing-agent compensation level. It is not one universal percentage across the final expense market.
For a deeper breakdown, see our guide to final expense commission levels for independent agents.
Commission levels vary by carrier, product, issue age, distribution relationship, and production. As one current example, Americo’s 2026 commission guidelines identify 120% as street level for its specified final expense product and age band, with higher levels tied to production requirements. That does not mean 120% is the street level for every final expense company.
See Americo’s current commission guidelines
The important lesson is to compare the actual compensation schedule for the specific carrier and product you are selling rather than choosing an FMO based on a generic commission promise.
Payout Modes
Carriers and agencies may offer different commission payment arrangements. Two concepts you will commonly hear are as earned and advanced commissions.
As Earned
As earned means commission is paid as qualifying premium is received. It generally reduces the amount of unearned advance that could later be charged back, but it also produces less cash up front.
Advanced Commission
With an advance, a carrier pays a portion of expected first-year commission before all of the corresponding premium has been collected. If the policy lapses or terminates during the advance period, unearned commission can become a chargeback.
Advance schedules are not universal. Review the current carrier compensation schedule, understand its chargeback rules, and maintain enough cash reserves to handle lapses.
Think in Unit Economics, Not Just Commission Percentage
A high contract does not automatically create a profitable final expense business. At minimum, track:
- Lead and acquisition cost
- Appointments or meaningful sales conversations
- Applications submitted
- Placement rate
- Average annual premium
- First-year commission received
- Persistency
- Chargebacks
- Net income after marketing and operating expenses
The number that matters is not what you were advanced. It is what you keep after acquisition costs, operating expenses, lapses, and chargebacks.
Final Expense Leads 101
Before buying leads, make sure you understand the final expense target market and the type of consumer each lead source is designed to reach.
You are only as good as your leads in the final expense business. If you don’t have a consistent source of leads, you will fail. The right number of leads depends on your lead source, contact rate, appointment rate, close rate, placement rate, average premium, and persistency. Instead of relying on an industry income promise, work backward from the number of presentations or meaningful sales conversations you need each week. I personally had the most success working direct mail, but like anything, marketing initiatives are always evolving. We’re now having really great luck with facebook leads. There are 4 common types of final expense leads.
Facebook Final Expense Leads
Facebook continues to grow as a popular lead source for final expense leads for agents. Here is what you should know. Not all leads are created equal and here’s why. Facebook is a different animal than google and running lead campaigns is constantly a moving target. Below are some considerations when getting Facebook final expense leads.
- What is the final expense target market? Does your lead provider give you any details?
- Are the leads TCPA compliant? What does TCPA even mean?
- Are the leads generated using Facebook default forms or directly traffic to a landing page to convert?
- What geography are you targeting
- What time are the ads running and what is the average time your respondents are filling out the forms?
- Are the leads delivered in real time or are you waiting for someone to download the leads and send them to you?
All of these elements can impact the quality and volume of leads you receive. Not many vendors will tell you everything because they fear you’ll leave them as a customer, which is a legitimate fear. Here’s my take on Facebook final expense leads… Use a vendor that knows what they are doing and let them continue to do it well. You are a final expense agent, not a lead generation guru. Business is all about surrounding yourself with those smarter than you. Let the lead generation experts do their job while you stay focused on how quickly you’re dialing your leads, following up, asking for referrals, door knocking, etc.
How much do Facebook final expense leads cost?
There is no reliable universal price for a Facebook final expense lead. Cost can change based on geography, targeting, creative, exclusivity, qualification, lead age, transfer method, and market conditions.
Instead of buying based on cost per lead alone, measure cost per contact, cost per appointment, cost per submitted application, cost per placed policy, and ultimately your acquisition cost after chargebacks.
Direct Mail Final Expense Leads
Direct mail final expense leads are generated through a letter with a postage-paid reply card completed by the prospect requesting more information on
or alternatives to the $255 social security pays upon death. The client must physically fill out the card and return it to the sender via mail. By physically completing the reply card, the client is much more likely to remember completing the form, greatly increasing your chances of setting an appointment. Direct mail response rates vary by list quality, geography, creative, offer, season, postage, and vendor. Measure the response and placement economics of your own campaigns rather than building your budget around a universal response-rate assumption. Direct mail costs change with postage, data, printing, volume, and vendor pricing, so calculate your current cost per response and cost per placed policy before scaling a campaign. Direct mail leads are often considered the best final expense leads as that is what the industry heavily relies on. We have been testing other types of final expense leads and can’t quite say which is best, but we’re starting to see some compelling trends that indicate you should diversify the types of final expense leads you are buying each week.
Best Direct Mail Companies
We have used numerous direct mail companies so it’s hard to determine who deserves the award for best. Below are the best direct mail companies we have directly used or our agent network has given us great reviews.
My good friend Glen Shelton created a great review of the best final expense direct mail companies, you can check it out
Telemarketed Final Expense Leads
Telemarketed final expense leads are generated through cold calling your target demographic and typically offering to provide information on new state approved burial plans. Some agents thrive on cold calling, but if this isn’t you, there are many third-party telemarketing firms both in the U.S. and internationally. The prospect commits to the lead over the phone with a promise an insurance agent will contact them within 24 hours. This is a much faster turn-around and about half the price as direct mail, but these leads have a much shorter shelf life to convert the lead to a sales appointment. So, it’s critical you follow up with telemarketed leads quickly; preferably the same day. Pricing for telemarketed leads varies substantially by vendor, exclusivity, qualification process, age of the lead, and whether the lead is an appointment, transfer, or data record. Verify the vendor’s current pricing and compliance process before purchasing. Our agents currently use a blend of telemarketed leads and direct mail, you can
.
Door Knocking Final Expense Leads
Door knocking final expense leads are not as intimidating as you might think. Frankly, they are highly effective if you can get over your fear of getting punched in the nose! 😉 All jokes aside, door knocking is highly effective for final expense sales. The difference between door knocking and setting final expense appointments over the phone is you don’t have a phone. Door knocking final expense is all about diversifying your prospecting efforts. If you have a stack of leads from previous weeks that you can’t reach by phone, go knock on their door when you’re in their area. It’s simple, you just have to step out of your comfort zone and do it. Plus, you’ll be addicted once you do it and see how effective it is in generating new sales. Door knocking final expense leads feel like they’re free, because you’re simply following up on direct mail leads you already purchased but couldn’t reach over the phone. It’s a great use of your free time in between other appointments. The agents that are consistently door knocking each week are absolutely out producing those that aren’t.
Door knocking script
Here is language and process I use when knocking doors.
- Organize all my leads in a stack.
- Enter them into a mapping software
- Go knock the route that takes me to all my leads in a circle from home to all my appointments and back home again.
When I’m at the door, I use simple language.
“Hello, Mrs. James? Hi, sorry to catch you off guard but my name is Drew Gurley and you had sent me this card a couple days / weeks ago. (show them the card)
“I was in your neighborhood meeting with some other clients and wanted to stop by and introduce myself so you could put a face with a name. Do you have 15 minutes for me to walk you through the information you requested?”
If they say no….
“I’m sorry, I wasn’t clear. I didn’t mean today as I’m fully booked. I will be here the rest of the week before I move to a new city. Are you available Tuesday or Thursday at 11:00 or 2:00?”
I have used this approach many times with great success. If you consistently integrate door knocking into your weekly sales activity, you’ll 100% see an increase in your numbers. Don’t be afraid of door knocking!
Organic Internet Final Expense Leads – Google
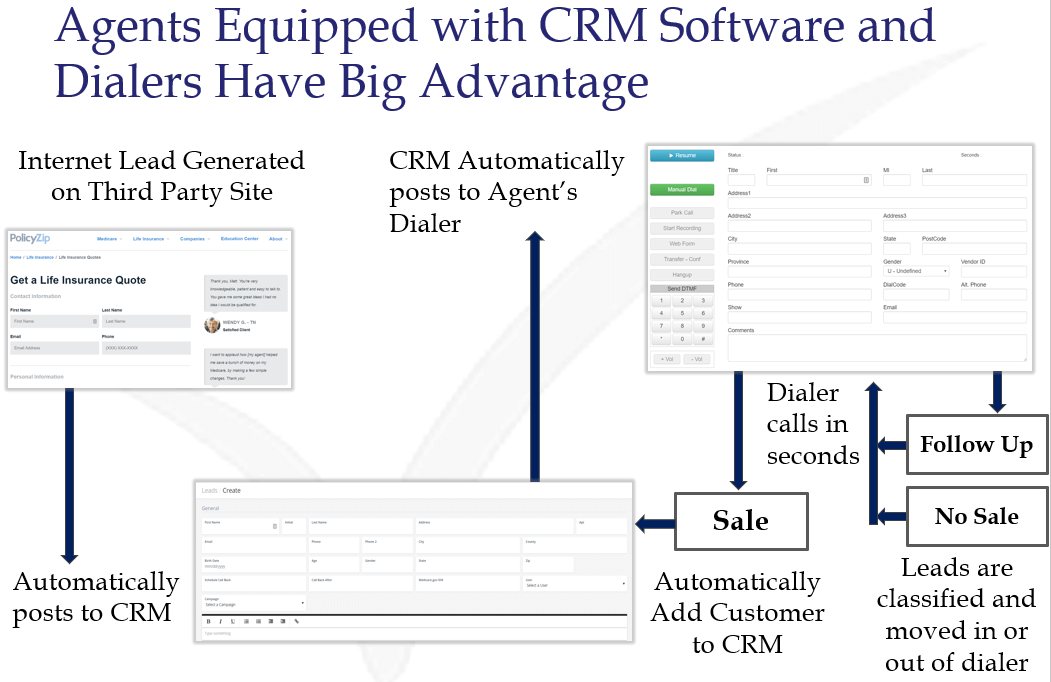
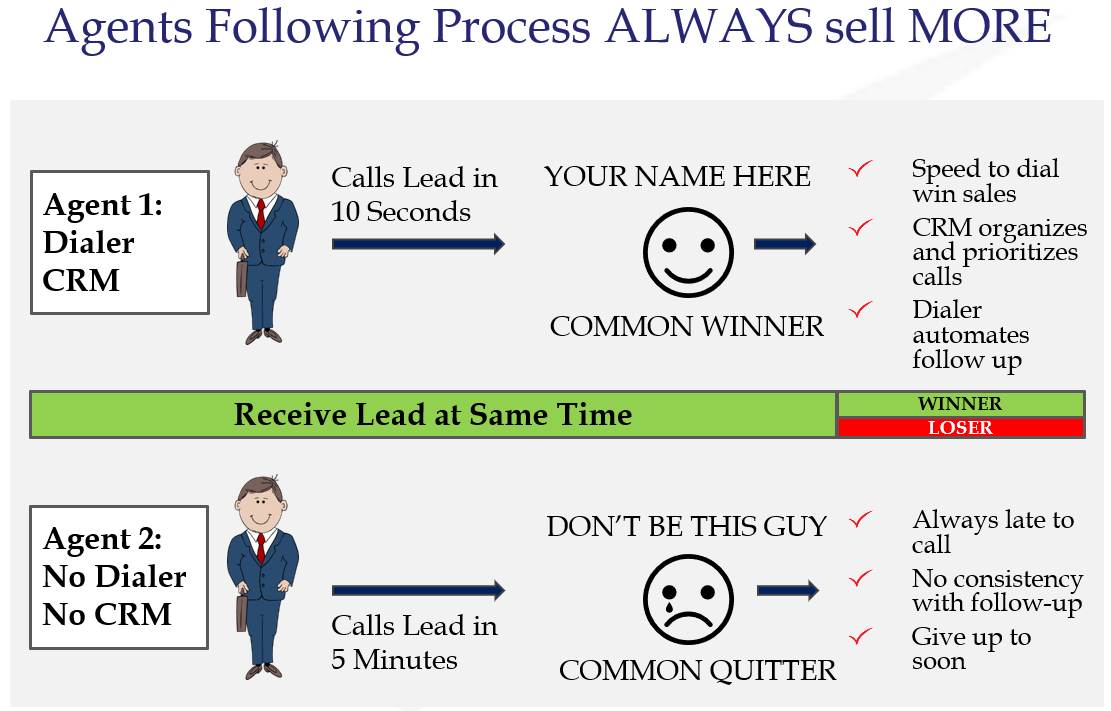
I hear this from agents just about every day: “The final expense market isn’t online.” Just because the typical final expense prospect is older than 50, don’t make the mistake of assuming they are not users of the internet. Millions of people buy insurance online, final expense included. They simply search for a website regarding burial insurance or funeral insurance. Those sites may offer final expense quotes or information and connect interested consumers with licensed agents. Pricing and distribution models vary widely, so agents should understand whether a lead is exclusive or shared, how old it is, and exactly what consent was captured. Internet leads are all about timing. These leads have an extremely short shelf life, so you have to strike while the iron is hot! Many agents working internet leads have an automated dialer that will call leads within 10 seconds of the consumer filling out the lead form online. The really good news here is these leads are often generated via SEO which is two parts great content and one part great links. You can do this yourself if you hire a good
Below is a quick look how the process works from how internet final expense leads are generated to the best way to work them.
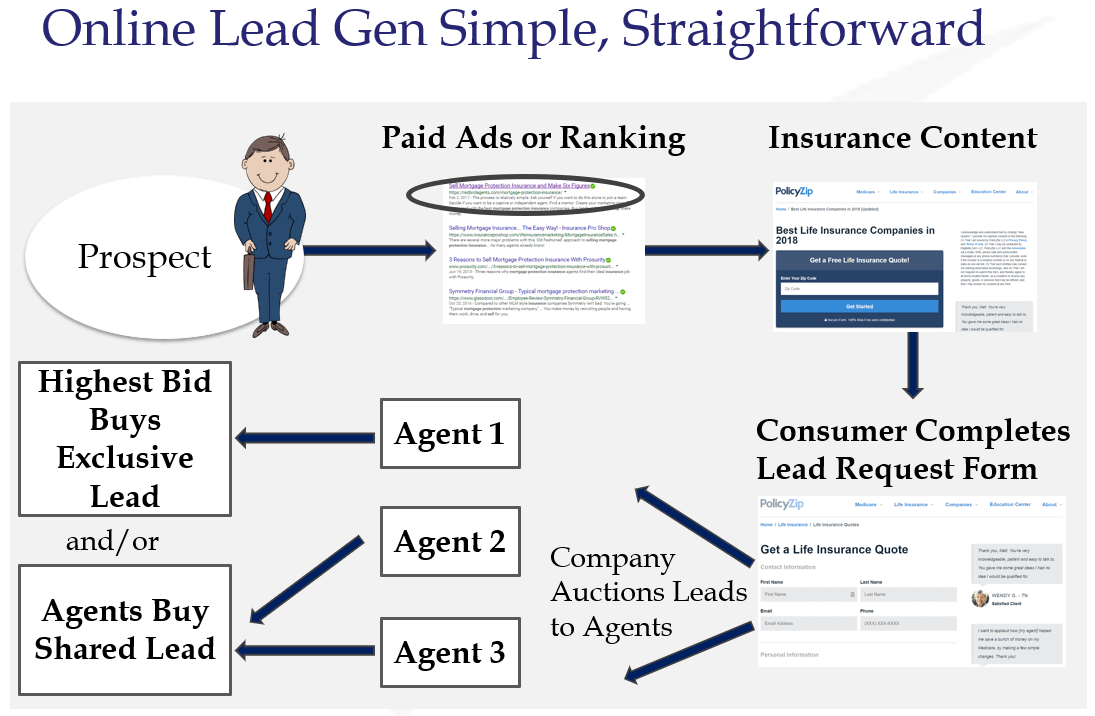
Process to sell final expense over the phone using internet leads.
Hopefully now you can better understand why it can be so difficult to sell internet leads over the phone.
How Many Leads Do I Need Each Week?
This is a loaded question because the answer depends on how you sell and what type of leads you work.
A better way to manage the business is to establish a weekly presentation or conversation goal and then calculate how many leads you need based on your own contact and appointment rates.
For example, if your goal is 20 presentations per week, track how many new leads, follow ups, referrals, and older prospects it actually takes you to generate those 20 presentations. After several weeks, you will have a much more useful number than an industry average.
The same principle applies to telesales. Track dials, contacts, meaningful conversations, applications, placements, and persistency. Your own funnel should determine how many leads you buy.
The key is consistency. Over time you will develop a larger database of prospects and follow ups, which means your business should not depend entirely on this week’s new lead order.
Final Expense Data: Make Sure You Buy Good Data
Another component of leads you need to understand is data. You need to make sure the final expense data lists you are buying are strong and fit each of your lead types. For example, how do you know the data you just purchased is current? How does the lead company filter the data? Do they include phone numbers? What types of guarantees are there and have they verified the address with the USPS? If there are multiple prospects in one house, are you sending one lead card or two?
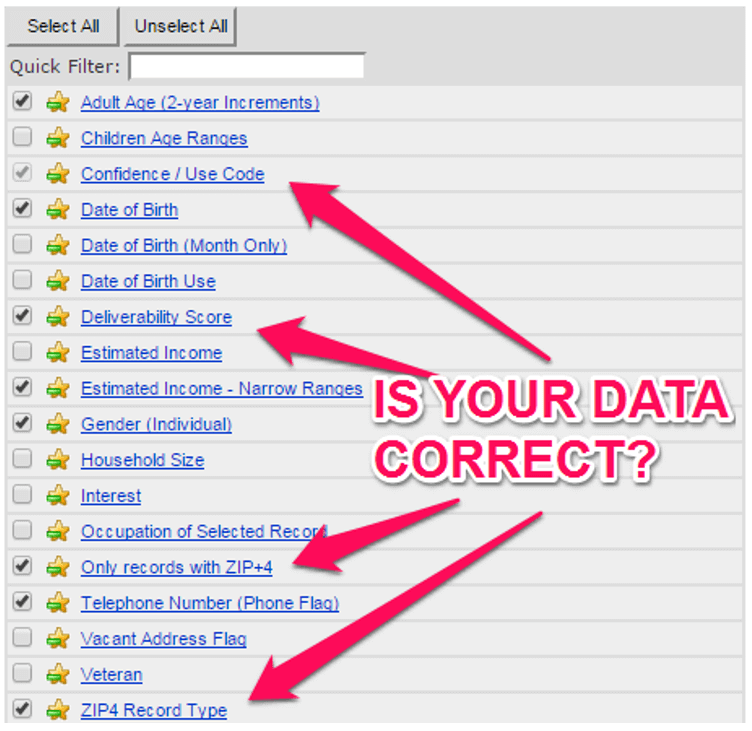
You need to make sure the vendors you are using are helping you succeed. If you aren’t sure how they are pulling your data together, pick up the phone and call the data company. Make sure they walk you through the best filters to capture the strongest data possible regarding your target market. The last corner you want to cut when creating your final expense marketing plan is data. You are going to encounter a lot of offers for FREE data. Buyer beware! Bad data is bad data, whether it’s free or not. Press the vendor on where the data came from and what filters were used. My suggestion is you call two or three data companies and tell them what you are trying to accomplish. They will not only have input on how to filter the data, but they’ll also help you understand the true costs of final expense insurance lead generation.
What is the Best Final Expense Lead?
Simple answer: multiple lead types working in unison can be one of the most effective ways to sell final expense. The golden ticket is consistent activity.
I personally had the most success working direct mail, but marketing initiatives are always evolving. The important lesson is not to become dependent on one source of prospects.
Your lead strategy should give you enough opportunities each week to consistently have conversations, set appointments, make presentations, and follow up with people you were unable to reach the first time.
How Much Should You Spend on Final Expense Marketing?
There is no single correct weekly lead budget. The right budget is the amount you can consistently fund while maintaining acceptable acquisition cost, placement, persistency, and chargeback results.
Do not evaluate a lead source only by its price. A more expensive lead that produces better contact, placement, and persistency can be more profitable than a cheap lead that never turns into placed premium.
Build a simple scorecard for every lead source:
- Total marketing spend
- Leads received
- Contacts
- Appointments or presentations
- Applications
- Placed policies
- Placed annual premium
- Commission received
- Chargebacks
- Net return on marketing spend
That is how you determine what your leads are actually worth.
Final Expense Sales Training
I don’t care what you’re selling, you need a strong insurance sales training foundation to get your business to the proverbial “Next Level”. Many new agents fast forward through final expense training because they believe it is easy to sell a small policy to pay for a funeral. Nothing could be further from the truth. While the premiums for the typical final expense policy are less than $60 per month, this is a significant sum for many target customers and, consequently, is an important decision for them. Below are some of the core components you need to learn during your final expense training:
- Overcoming rejection and failure
- Appointment Setting: How to set your final expense sales appointments.
- Sales Presentation: What to say when you’re sitting at the kitchen table.
- Phone Script: How to set your appointments over the phone.
- Objections: How to structure your presentation so you can prevent objections from occurring.
- Closing: How to help your client make the purchase decision with you.
- Sales Psychology: it’s not just what to say, but why and when to say it.
- Leads: How to properly work your final expense leads
The important distinction: buying leads and working leads are two different skills. A good lead source cannot make up for poor follow up, and a great sales process cannot help you if you do not have enough people to talk to.
Learn How to Work Final Expense Leads
If you want to be a successful final expense agent, you need to know how to work your leads.
The most important part of a lead strategy is having a repeatable follow-up process. Not every prospect answers the first call, and different lead sources require different follow-up.
Your plan should define:
- How quickly a new lead is contacted
- How many follow-up attempts are made
- Which channels the consumer actually consented to receive
- How Do Not Call and entity-specific opt-out requests are handled
- How older leads are recycled
- How referrals are requested
- How every lead source is measured through placement and persistency
Compliance matters here. Do not assume that a phone number being absent from the National Do Not Call Registry automatically makes every type of call or dialing method permissible. Federal rules, state rules, consent requirements, calling technology, prerecorded or artificial voice use, and a consumer’s prior opt-out can all matter.
The FTC says covered sellers and telemarketers generally must scrub applicable calling lists against the National Do Not Call Registry at least every 31 days and maintain their own entity-specific Do Not Call procedures. The FCC also regulates telemarketing calls and texts.
Review the FTC Telemarketing Sales Rule guidance and have qualified compliance counsel review your specific lead-generation and dialing process.
Knowing how to work your leads is half the battle; the other half is showing up and consistently executing your process.
Final Expense Presentation Outline
What you’ll learn is everyone has a similar approach to selling final expense, and along the way you’ll learn words that work with your style. Below is a basic outline of your presentation in the home.
Build Rapport
This starts from when you’re calling to set the appointment to the moment you’re knocking at their door. Always be on time, dress appropriately, and make sure you’re confident in your abilities. You don’t need to spend the first 30 minutes on a warm up. Build rapport quickly and get them into the presentation. You can do this easily by finding common interests.
“Hello Mrs. James, I’m Drew Gurley, I called you last night about the card I received from you about the final expense program available to seniors. How are you today? Great, hey what’s you’re dog’s name?”
By doing this you’re able to then pull from your personal experiences and respond accordingly. For example, “I’ve grown up with dogs and coming home to a happy furry friend is about as good as it gets, wouldn’t you agree? Seems simple and it is, just make sure you’re genuine about it. Find something that triggers your mind to connect, and talk to them about it. Getting into rapport should take 10 minutes or less and from that point you can transition into your sales presentation.
Build the Need
The easiest way to kick this off is by reading the card or ad they responded to. This is something they recently completed and it will trigger their memory as well as start the process of identifying the problem, discovering opportunity, and qualifying for coverage. Try not to use Yes or No questions, and instead go for a more open ended approach.
“How did the death of your loved one impact your family?”
“What was the hardest part about the funeral planning process?”
Set the Expectation
It’s always important to tell them what you intend to do.
“Here is how our program works, Mrs. James. Our program is designed to help you take a few dollars each month and set them aside to have the entire funeral expense covered before it ever happens.”
It’s important during this phase to make sure you’re consistently explaining the facts and benefits of the program. And, being extremely courteous along the way. Here are some examples I learned from Jim Mall, one of the greatest final expense sales trainers.
Fact Statements:
The exact face amounts, benefit timing, guarantees, and underwriting class depend on the policy you are presenting. Use the carrier-approved language for the specific product rather than making a universal promise. Here is the full breakdown.
Fact: Immediate Benefit
Benefit: If you pass away, the insurance company pays your family.
Fact: How are you going to die? It can only happen 3 ways: Natural Accidental, or Suicide
Benefit: No matter what happens, we can design a solution that will pay your family.
Fact: 100% guaranteed
Benefit: Your family gets all the money to use as needed, it’s not in the control of the funeral home
Fact: Cash Benefits
Benefit: Your family receives the money, not the funeral home. We don’t cut checks to the cemetary, the hospital, nursing home, or even your utility companies. We pay the benefits directly to you.
Fact: Guaranteed Benefits
Benefit: One thing in life that we know is guaranteed is that we’re all going to pass away, something we already covered. When you die, you family will get paid.
Fact: Life insurance death benefits are generally excluded from a beneficiary’s gross income under federal tax rules, although exceptions can apply.
Benefit: In a typical personally owned life insurance situation, the beneficiary generally receives the death benefit without including it as taxable income. Do not provide individualized tax advice.
Explaining these facts and benefit is a great way to recap your discussion about final expense. The next step is giving them your three guarantees.
Fact: Your payments will never increase as your age or health changes
Benefit: You’re not surprised on any given month when your premiums are collected. It’s always the same, predictable amount.
Fact: You benefits will never decrease.
Benefit: Your family know exactly how much they will receive to properly plan your burial.
Fact: Your policy cannot be cancelled, no matter how old or sick you get. As long as you make your payments on time each month, you’re policy will remain active. The best way to do this is to have your bank send the premiums to the insurance company every month for you.
Benefit: We cannot take it away, especially during critical times like illness or accidents. The plan is there when you need it.
Closing the Sale
Once I have made it through my presentation and confirmed the facts and benefits above, I pull an application out and state the following.
“How long would it take you to save $10,000 at one or two dollars per day?”
“Our program gives you the $10,000 in the snap of a finger when you pass away, simply through transferring $2 per day to an immediate balance of $10,000.”
“Let me get some additional information from you, then we’ll decide which program you will be comfortable with.”
From here I ask the health questions on the application and I prepare 3 options starting with the death benefit amount they requested on their card. If you have covered your facts and benefits correctly, used open ended questions, and built adequate trust, your closing should go very smooth.
Final Expense Underwriting
Do final expense policies require a medical exam?
Many final expense policies do not require a traditional medical exam. Simplified-issue products may still use health questions, prescription history, database checks, and other underwriting information. Guaranteed-issue products generally avoid medical underwriting but may limit the natural-death benefit during the early policy years.
If there’s any magic in selling final expense I believe it is here. Knowing how your carriers deal with various health conditions doesn’t happen overnight, but those who master it are much more equipped to write large amounts of new business. If you’re brand new, here’s a link to an article we did regarding common
medical conditions you’ll come across in the field
. This will help you get a baseline understanding. If your client is an insulin-dependent diabetic, you should know which company to choose. If they were diagnosed with cancer four years ago, you need to know where to turn. Knowing how to
navigate the carrier underwriting
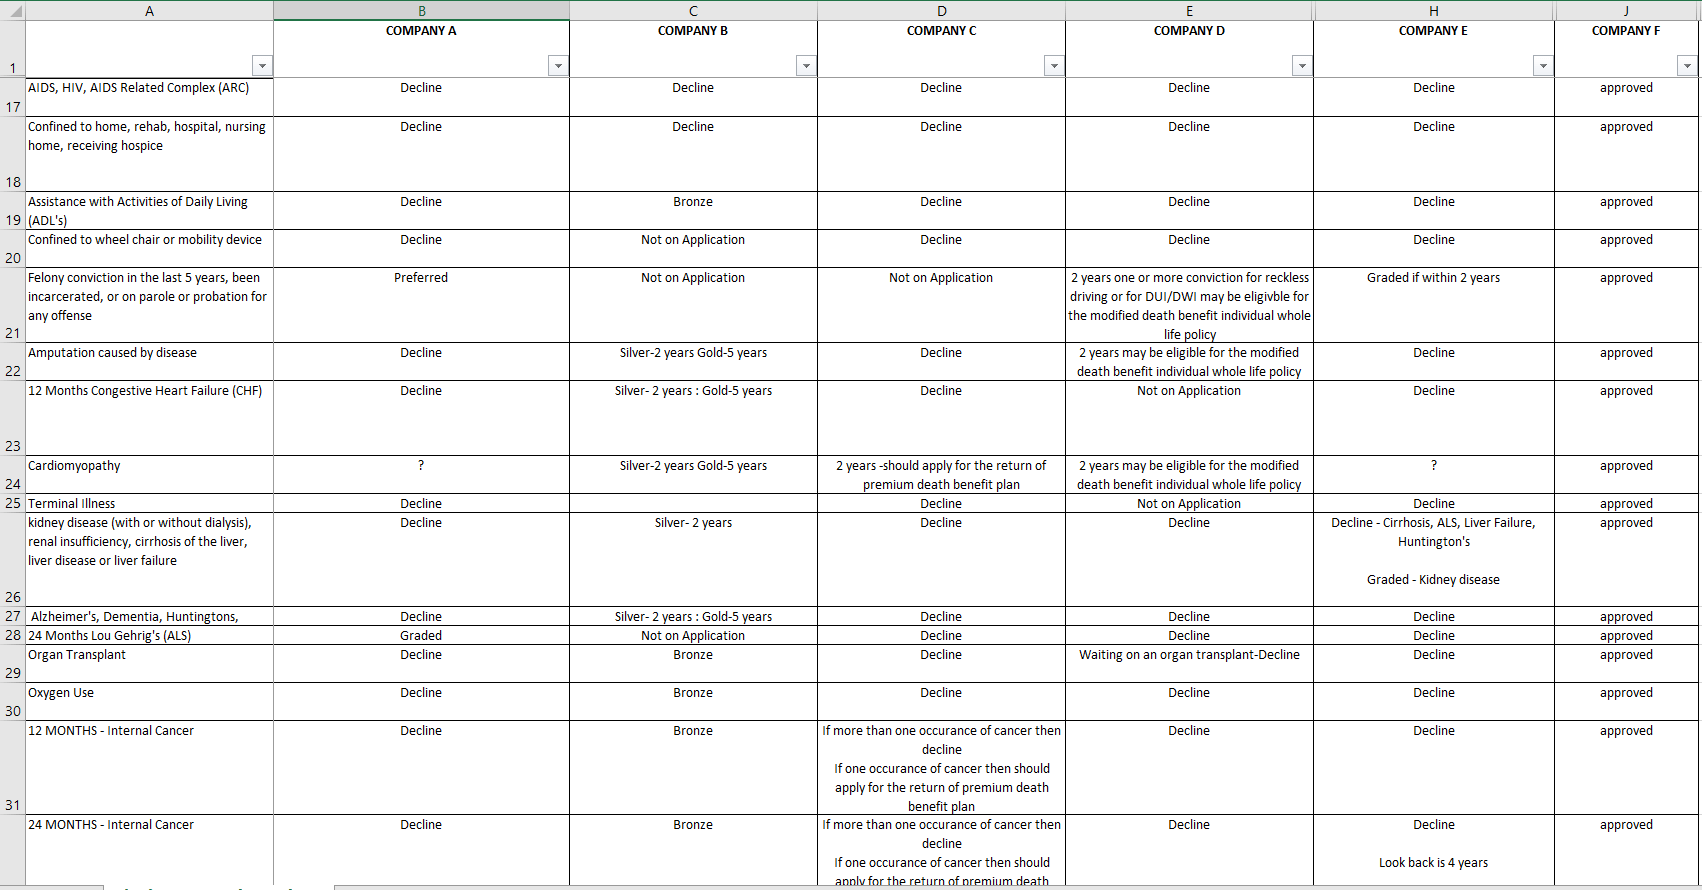
separates the good final expense agents from the great! Here’s how to create a final expense underwriting cheat sheet:
Step 1:
Get copies of each of your core final expense carrier health questions.
Step 2:
Create a spreadsheet:
- List you core final expense carriers across the top so each company has its own column (starting in column B). List them from left to right in order of importance (e.g. your top choice carrier goes in column B, etc.).
- Starting with the first row the names of carriers, list the final expense health questions and associated time frames in each row of Column A. You should now have chart that has companies on the top, conditions down the side and a bunch of blanks cells to fill in.
Step 3:
Complete one carrier at a time and enter the following choices in each cell based on the underwriting question listed on the application.
- Level
- Graded
- Modified
- Declined
Step 4:
Once completed, go to your primary final expense carrier column:
- Highlight every cell labeled “Level” in column B in bright green. This makes it easy to instantly know which company you should use first in every scenario, especially when your cheat sheet has a ton of carriers listed.
- Highlight all “graded” cells yellow
- Highlight “modified” cells blue
- Highlight “decline” cells red
Now that you have all your companies and health questions organized, you can easily find which company to use in every possible scenario. Why don’t I offer a free final expense cheat sheet for you to download? Because you need to have skin in the game and put the work in. If you’re not willing to create this on your own, then you’ll likely cut corners again on another important part of your business. Cutting corners leads to failure, so don’t do it. Creating a final expense underwriting cheat sheet is a great exercise as you’ll learn a lot about the final expense companies you are carrying around in your sales bag. Below is a screen shot of what a hypothetical final expense cheat sheet looks like.
Common Final Expense Underwriting Questions
The conditions you will encounter have not changed nearly as much as the carrier answers have.
Diabetes, COPD, cancer history, oxygen use, heart conditions, kidney disease, age, and identification requirements are all examples of issues that can affect placement. But a static list saying “Carrier X takes condition Y” can become outdated quickly.
Instead, collect the details that actually drive underwriting:
- Exact diagnosis
- Date of diagnosis
- Current medications and what each medication is treating
- Hospitalizations, procedures, or complications
- Current treatment status
- Relevant look-back periods
- Age and state
- Other health conditions that may affect the decision
Then compare those facts against the current carrier field underwriting guides and application questions.
If you’re brand new, review our guide to common medical conditions life insurance producers should know and learn how to navigate impaired-risk underwriting.
This is exactly why I recommend building your own underwriting cheat sheet instead of downloading somebody else’s old carrier list. Carrier products, questions, look-back periods, and decisions change.
Medications You Should Know When Selling Final Expense
One of the things you’ll learn on your journey of final expense sales is common medications. Below are some of the common medications you will come across in the field.
- Lisinopril: Used to treat high blood pressure and heart failure.
- Carvedilol: This is a beta blocker which is used to treat high blood pressure as well as congestive heart failure (CHF).
- Simvastatin: Common cholesterol medication used to reduce the risk of heart attack, stroke and other conditions.
- Metformin: Oral medication for diabetes treatment.
- Losartan: Commonly treats high blood pressure.
- Metoprolol: Commonly used to treat chest pains (angina), heart failure, and high blood pressure.
- Atorvastatin: Commonly used to lower cholesterol and reduce cardiovascular risk.
- Gabapentin: Commonly used to treat seizures and relieve nerve pain.
- Glipizide: Used for treatment of diabetes.
- Novolog: Used for treatment of diabetes.
- Hydrochlorothiazide: Treats high blood pressure.
- Lantus: Treats diabetes.
- Lasix: Congestive heart failure.
- Furosemide: Congestive heart failure.
- Depakote: Treats seizure disorders.
- Warfarin: Brand name for coumadin which is a blood thinner.
This is just a glance at the many drugs you will come across in the field. It’s always important to remember to ask what other conditions someone might have in conjunction with their current pre-existing conditions. Medications also often have a dual purpose so it’s important to ask your prospect what they are using each medication for so you’re not surprised when you try to get the policy approved.
**SALES TIP** This is a great moment to show your clients your high attention to detail and build confidence that you are the agent they should be working with.
Final Expense Telesales
Can you sell final expense insurance over the phone?
Yes. Final expense can be sold remotely when the carrier supports the required application and authorization process and the agent follows applicable licensing, carrier, telemarketing, consent, and call-recording requirements. Telesales requires a different operating process than selling face to face.
Telesales (selling final expense over the phone) is a hot topic! More and more agents reach out to us with questions regarding how to get started in final expense telesales because they hear direct mail responses are smaller and prices are higher. Plus, they see the potential for generating leads on Facebook and the appeal for remote selling over the phone get’s even bigger. And, the market is growing for prospects willing to buy final expense over the phone. In fact, there is so much detail that goes into selling final expense over the phone, we could probably write an entire how to guide on this topic alone. Here’s what you need to know at a glance.
Final Expense Telesales: How to Sell Final Expense Over the Phone
Find a Mentor
Selling final expense over the phone is
NOT
the same as selling in the field. Telesales can be hard to get used to which is why a mentor is SO important. You need to align yourself with someone who has proven success with final expense telesales so they can teach you exactly what to say, why to say it, and how to master the one call close. There are a couple great places to learn the ins and outs of final expense telesales. If you are interested in selling final expense over the phone, align yourself with an organization that can demonstrate a repeatable process for lead handling, compliant calling, electronic applications, placement, and persistency. Telesales is not simply field sales with the kitchen table removed.
Want to Get Started in Final Expense Telesales?
Contract with Carriers That Support Your Remote Sales Process
This is critical for scaling a telesales operation.
Electronic applications, identity verification, electronic signatures, voice authorization, payment setup, and remote application procedures vary by carrier and product. Do not rely on an old list of “voice signature carriers.” Verify the current process directly with each carrier before building your workflow around it.
Telesales Compliance
The first rule of selling final expense over the phone is to make sure your process is compliant.
The TCPA, FTC Telemarketing Sales Rule, National Do Not Call requirements, state telemarketing laws, carrier rules, consent language, call-recording laws, and the technology used to place a call can all affect what is permitted.
One important recent development: in January 2025, the U.S. Court of Appeals for the Eleventh Circuit vacated the FCC’s 2023 rule that would have imposed new one-to-one and logically-and-topically-related consent restrictions for certain robocalls and robotexts. That did not eliminate the existing TCPA, prior-express-written-consent requirements applicable to certain telemarketing robocalls or other federal and state requirements.
Do not treat a lead vendor’s statement that a lead is “TCPA compliant” as your entire compliance program. Review the actual consent language and available proof of consent, understand how the lead was generated and distributed, honor opt-outs, and have qualified counsel review your process.
FTC Telemarketing Sales Rule guidance
Customer Relationship Management System (CRM)
Telesales requires extreme organization! You have to stay organized so you know how many times you have attempted to call your clients or prospects. You should also make sure the CRM you choose can integrate with your dialer, it will make your life much easier. My suggestion would be review the dialers first and then find out which CRM companies they are already integrated with.
Sales Dialer
A dialer can dramatically improve efficiency, but the type of technology you use matters from a compliance standpoint.
Before selecting a dialer, determine how calls will be initiated, whether prerecorded or artificial voice technology is involved, whether text messaging is included, how consent and opt-outs are stored, how state-specific restrictions are handled, and how call recordings are managed.
Your CRM and dialer should make it easier to document compliance and follow up, not simply make it possible to place more calls.
Confidence
Selling final expense insurance over the phone takes confidence and is something you absolutely need to practice building. Some say you have as little as 30 seconds to make your first impression with lead on the other end of the phone. I recently read a comment online from Jeff Root where he shared some excellent words.
“In telesales, you have 30 seconds to make an impact. If you open your call with a low or monotone voice, no engagement or awkward pauses, you’ll have a hard time engaging with your prospect.
Open your call with an overly positive and confident tonality – conveying that you are going to facilitate a streamlined process.
It’s less about what you say and more about how you say it.
The key is starting the call off right.”
Below is a list of some of the more popular dialers to use for final expense telesales.
- VanillaSoft
- Five9
- Sales Dialers
- Velocify
- Leadsrain
**SALES TIP** The magic of this is getting a system that allows you to consolidate your leads in one place and build in a process of automation to keep your communication consistent. For example, you should always be texting your leads as a means of touch point.
Want to Get Started Selling Final Expense Insurance Over the Phone?
Captive Agent vs. Independent Agent
Both models exist, but independent distribution is especially important in final expense. In the 2025 LIMRA–LIC survey, independent distribution accounted for 75% of the policies reported by participating carriers.
I know you’re wondering: “How much can I make selling final expense”? Aside from your work ethic, it’s going to come down to how you choose to get into the business. There are two main ways you need to consider. First, ask yourself this question and answer HONESTLY: Are you instinctively a self-starter or do you need a cheerleader on a daily basis to get you fired up for the day? If you answered self-starter, then going independent would be a great place for you to start. If you need the cheerleader then I would highly consider going captive, at least until you get your feet wet and build some experience and success. Fooling yourself during this part of the process is just setting you up for failure. Don’t do it. Let’s make this a little more real and look at both scenarios.
Captive Final Expense Agent
When you’re a captive agent, you work for an agency and do not own your book of business. This means that every customer you write is owned by your agency and not by you. Why does this matter? When you decide to move on, your book of business does not go with you and neither will your renewal commissions. The other part about being captive is understanding you are going to get paid less. You’re probably thinking, “why would someone ever agree to getting paid less?” Part of being captive is that the agency has typically invested heavily in infrastructure to support you, whether it’s training, marketing, or IT. You should expect to get paid less when you are getting a high level of support from your agency. Below are some examples of the level of support you can expect in a captive agency:
- Extensive hands on training and mentorship.
- Consistent ride-along sales support.
- Leads, preset appointments, or both provided at a significant discount or no cost.
- Other benefits such as base salary, health insurance, and travel allowances.
The captive sales model allows you to focus on selling and never having to worry about how to get life insurance leads again. As mentioned above, in exchange for this level of support you will receive a much lower compensation. Remember, there is always a cost to doing business. You can either pay for it out of your pocket and be your own boss, or you can trade your ability to sell and have a captive agency provide those services for you. Being a captive final expense agent certainly has its perks; it’s up to you to decide if it’s the type of environment you need in order to become a top final expense producer.
Independent Final Expense Agent
Independent agents are 1099 contractors to the various final expense companies. In most cases, your commissions are paid to you directly from the insurance companies and not the agency/FMO you’re working under. As an independent agent, you will be provided access to the best final expense insurance companies and a variety of final expense lead sources. Pay close attention to my words, “sources”. This means you are responsible for your own expenses and your upline will not be covering those costs for you. You’ll also be responsible for all of your business expenses and operating costs. When you’re independent, you’re a business owner, which is why I said going independent is great for self-starters! Independent agents carry more responsibility as well as earn significantly higher commissions than a captive agent; typically, at or near street level.
Final Expense Sales Incentives
We love sales incentives, and there are lots of opportunities to earn them selling final expense. If you’re a top producer these companies will literally allow you to travel all over the world. Below are some of the various incentives you can expect to receive in the final expense market:
- Trips around the world
- Gas cards
- Monthly cash awards for top final expense producers
- Fast start FREE LEAD PROGRAMS
- Rewards trips (IMO and Carrier sponsored)
- Monthly lead credits
Managing Your Book of Business
Arguably the easiest way to keep your renewal income each year is to stay in touch with your customers by paying close attention to your book of business. We preach customer experience in all of the sales models at Redbird, and final expense is no different. Depending on the sales model you choose, holiday cards, thank you cards and client review cards should be sent to your clients annually. This makes it easy for you to maintain touch points with your clients while staying focused on working your final expense leads each week. Some agents will say they don’t see an impact in their business. It’s our belief that you should always provide a premium customer experience, so sending cards should be less about you and more about making your customers feel appreciated. Also, here’s a trick that always works… Hand address and use stamps. This will increase your open rates and further solidify your relationships with your customers.
Want to Start Selling Final Expense?
Redbird helps independent agents access carrier contracting, sales resources, training, and tools for building a profitable final expense business.
Frequently Asked Questions (FAQ)
Is it hard to sell final expense?
It’s not necessarily hard, but it takes mental determination to do really well. You need to fully understand that this is a process business and if you’re not starting out learning a defined sales process, then you’re likely in the wrong place. Selling final expense is “easy”, learning how to sell it at a scale that is profitable and provides you the financial freedom you are seeking is the part that takes the blood, sweat, and tears!
Can you get final expense insurance training online?
Absolutely. I would suggest working with Jim Mall’s program, 1 and Done. Jim Mall is a final expense pioneer and his selling method is exactly what I learned and still use to this day when I’m out selling. It’s a methodical process that will give you every piece of information you need to take a stack of leads and start earning a living. If you memorize his stuff and put it to practice in the field, your results will amaze you.
What does “advanced” commissions mean?
Advanced commissions are commissions paid before all of the premium used to calculate that commission has been collected. If the policy terminates early, the unearned portion may be charged back. Advance schedules and chargeback rules vary by carrier.
What are “as earned” commissions?
As-earned commissions are paid as qualifying premium is received rather than being substantially advanced up front. The exact calculation and timing depend on the carrier’s compensation schedule.
What is a chargeback?
If you’re client cancels before those 9 months of premium have been paid, you’re 9 month advanced commissions will become a chargeback that you will need to pay back to the insurance company. Each company has different chargeback rules, so make sure you’re paying attention to the fine print in your contract with the final expense company.
What is a release?
A release is a written authorization from another upline organization allowing a contracted agent to move their contract to another wholesaler or agency.
This is why I always urge agents to do their homework before choosing an agency or FMO to work under. You should have a clear understanding of any potential restrictions you might experience.
Some places have an open release policy which makes a lot of agents feel good and some don’t. Those that do not usually have some type of proprietary process that takes time and money to activate a new producer. In that case, getting a release is tough because they want to recoup their time and money for training and support.
How do I switch to a new FMO?
First, you need to determine if you need a release. Most of the time the rule is that you don’t need a release if you haven’t written business with a specific final expense company for 6 months. In those instances, you can likely recontract with any upline or FMO or your choice.
If you have written business within 6 months, you’ll need to get a signed release from your previous FMO.
Can I switch FMOs to get higher commissions?
In short, yes, but it’s extremely frowned upon and many final expense companies do their best to keep that from happening. What you’ll find when you trying to switch is the insurance companies can make you wait anywhere from 6 to 12 months before your new FMO can increase your commission level.
Make sure you understand the rules before you decide to jump ship over a few bucks…another reason you need to shop around before making your decision.
Don’t say I didn’t warn you! 🙂
Do agents really door knock?
Heck yeah we do!
Door knocking is an integral part of your sales prospecting process and a core element in nearly every top field agent selling in the final expense market.
Don’t let anyone fool you, door knocking is still a very effective part of the prospecting process, especially in final expense field sales.
What does LOA mean?
LOA means licensed only agent.
If you are on an LOA contract, that means all of your commissions and future commissions are paid to your agency who then pays you.
This is the typical setup in a captive setting. Most of the time independent agents will be paid directly by the insurance company and not from their agency or upline.
If you’re considering a captive arrangement that requires LOA contracts, you should closely understand your vesting schedule for your future renewals.
Final Expense Sales Process At a Glance
Don’t let an easy sales process make you think it’s an easy business. Final expense sales can and is often mentally exhausting when you don’t stay focused. Here is a condensed version of everything we discussed in this article
- Get contracted
- Buy leads EVERY WEEK. You ultimately should expect to be spending around $1,000 per week on your expenses and the majority of that cost will be leads.
- Master a consistent final expense sales presentation for face-to-face sales and telesales.
- Set a goal of having 15-20 sit down presentations every week
- Be courteous and patient
- Exercise caution when writing direct express or credit card business (it rarely sticks on the books and will cost you a lot of money in charge backs)
- Understand your insurance company point of sale interview process
- Track your commissions to ensure the carriers are paying you correctly
Conclusion
You can also find Redbird’s calculators, scripts, and training resources in the Insurance Growth Toolkit.
Learning to sell final expense insurance is not that hard, you just need to dedicate the time to become an expert. Final expense insurance sales is one of the fastest growing sales models available and the market continues to grow. Below is a recap of what our team believes are the keys to learning how to be successful selling final expense insurance:
- Stay focused and don’t get distracted.
- Don’t reinvent the wheel; there are too many people willing to help you replicate their system.
- Interview and find a final expense FMO that fits your needs… be selfish and patient.
- Understand the various final expense leads available.
- Create a sales and marketing plan to work your leads.
- Commit to training and become an expert. Remember to use your script to not only know what you say, but why you’re saying it.
- Don’t get greedy. If you take your time and plan out this business, you should never have any issues getting the commission levels you deserve.
Get comfortable with a sales model, find a mentor and absorb everything you can. If you’re not happy, change it. If you’re fired up, keep attacking! Put yourself in the best position to succeed and lean on those that are willing to help you. We would love the opportunity to partner with you,
to learn more.
Want to sell your final expense agency?
Final Expense Agent Resources
Use these Redbird resources to go deeper on the parts of the final expense business that matter most to your agency.