Indexed universal life insurance can be one of the most flexible permanent life insurance products available to agents, but it is also one of the easiest products to misunderstand, illustrate incorrectly, or position poorly.
This guide was built for insurance agents who want to understand how indexed universal life insurance works, how IUL policies are designed, how agents get paid, how to run and review illustrations, how to generate IUL opportunities, and how to build the support system needed to sell IUL responsibly.
Whether you’re learning indexed universal life for the first time or already writing IUL business, use this as a working resource for building and improving your IUL practice.
How Do You Start Selling Indexed Universal Life Insurance?
Selling IUL successfully requires more than getting contracted with a carrier. You need product knowledge, case design support, carrier access, a prospecting system, and a repeatable process for taking a case from initial conversation through placement.
The IUL Sales Process
- Learn how IUL works.
Understand indexing, cash value, policy charges, death benefit options, policy loans, MEC rules, and the difference between guaranteed and non-guaranteed values. - Choose your distribution model.
Determine whether you will operate as a captive or independent insurance agent and what carrier access you need. - Find the right IUL support.
Work with a BGA, IMO, or FMO that understands IUL case design, underwriting, illustrations, advanced markets, and placement. - Get contracted.
Build carrier access around the types of clients and cases you intend to serve instead of simply collecting contracts. - Learn case design and illustrations.
Understand funding strategies, solve options, death benefit design, policy loans, and how different assumptions affect long-term policy performance. - Build your pipeline.
Create repeatable prospecting channels through existing clients, referrals, centers of influence, business owners, and strategic partners. - Submit, place, and review business.
Manage underwriting, outstanding requirements, placement, and ongoing policy reviews after the sale.
IUL Agent Resource Guide
You don’t need to read this entire guide every time you have an IUL question. Jump directly to the part of the sales process you’re working on.
Learn IUL
Understand indexing, cash value, policy charges, crediting methods, floors, participation rates, MEC rules, and policy loans.
Design an IUL Case
Learn how client objectives, premium, death benefit, funding duration, age, and cash value goals affect policy design.
Run IUL Illustrations
Understand WinFlex, solve options, guaranteed values, non-guaranteed values, distributions, and illustration review.
Understand IUL Commissions
Learn target premium, first-year compensation, commission advances, bonuses, and how IUL compensation is calculated.
Generate IUL Opportunities
Build a pipeline using existing clients, policy reviews, referrals, centers of influence, and strategic partnerships.
Apply IUL to Real Cases
Explore business owner planning, buy-sell funding, key person insurance, living benefits, and other IUL scenarios.
How Does Indexed Universal Life Insurance Work?
Indexed universal life insurance, commonly called IUL, is a form of permanent life insurance that combines a death benefit with cash value accumulation.
Like other forms of universal life insurance, IUL generally provides flexibility around premium payments and death benefit design. What makes indexed universal life different is the way interest may be credited to certain portions of the policy’s cash value.
Instead of directly investing policy cash value in the stock market, an IUL can offer crediting strategies linked to the performance of an external market index, such as the S&P 500 or another index offered by the insurance company.
Why Agents Use IUL
Depending on the carrier and product, an IUL may provide:
- Permanent life insurance protection.
- Potential cash value accumulation.
- Flexible premium structures within policy limits.
- Multiple death benefit options.
- Indexed interest crediting strategies.
- A contractual floor on many indexed strategies.
- Access to available cash value through withdrawals and policy loans.
- Potential living benefit riders.
Those benefits also come with complexity.
Policy charges continue regardless of index performance. Caps, participation rates, spreads, bonuses, multipliers, loan provisions, and other policy features can affect actual results.
Some non-guaranteed policy elements may also change over time.
IUL Terms Every Agent Should Understand
You don’t need to sound like an actuary, but you should be able to explain these concepts in plain English.
Cap
A cap is the maximum indexed interest rate that can be credited under a particular indexed strategy during the applicable crediting period.
For example, if the strategy has a 10% cap and the applicable index calculation produces a 15% gain, the indexed credit may be limited to 10% before considering any other applicable policy provisions.
Floor
A floor establishes the minimum indexed interest credit under a particular strategy. Many IUL strategies use a 0% floor.
Participation Rate
A participation rate determines how much of an applicable index result is used in the crediting calculation before considering other applicable policy provisions.
For example, a 120% participation rate applied to a 5% index result would produce a 6% result before applying any cap, spread, or other applicable terms.
Spread
A spread is an amount subtracted from an index result when calculating the interest credit under certain indexed strategies.
Cost of Insurance
Cost of insurance, commonly called COI, is a charge associated with providing the life insurance protection inside the policy.
Age, underwriting classification, net amount at risk, product design, and other factors can affect mortality charges.
Cash Value
Cash value is value accumulated inside a permanent life insurance policy.
Cash value and cash surrender value are not necessarily the same number.
Cash Surrender Value
Cash surrender value is generally the amount available if the policy is surrendered after applicable surrender charges, loans, and other adjustments.
Indexed Interest
Indexed interest is interest credited according to the index calculation and contractual provisions of the selected indexed strategy.
Fixed Account
An IUL may also offer a fixed account that credits interest according to the carrier’s fixed-account provisions instead of an indexed strategy.
Modified Endowment Contract
A Modified Endowment Contract, commonly called a MEC, is a life insurance contract that fails the applicable 7-pay test under federal tax law.
The policy can still be life insurance, but MEC status changes the tax treatment of distributions.
Target Premium
Target premium is a carrier-defined premium amount commonly used to calculate agent compensation.
Target premium is not necessarily the same as annual premium or the amount a client should pay to accomplish a particular policy objective.
Retirement Planning Concepts IUL Agents Should Understand
If you’re discussing IUL as one component of a retirement strategy, you need to understand the financial landscape surrounding the product.
You don’t need to pretend to be the client’s CPA, attorney, or investment advisor. But you need enough knowledge to understand where life insurance may or may not fit.
Taxable Assets
Clients may own assets outside qualified retirement plans that can create capital gains or other tax consequences when sold.
- Stocks held in taxable accounts.
- Mutual funds held in taxable accounts.
- Real estate.
- Business interests.
Tax-Deferred Retirement Accounts
Agents frequently encounter clients with:
- Traditional IRAs.
- SIMPLE IRAs.
- SEP IRAs.
- 401(k) plans.
- 403(b) plans.
- 457 plans.
Roth Accounts and Other Tax-Favored Strategies
- Roth IRA.
- Roth 401(k).
- Municipal bonds.
- Cash value life insurance.
Don’t Ignore the Employer Match
If a client has access to an employer retirement plan with a meaningful employer match, make sure the client understands the value of that benefit.
An IUL conversation should not begin with the assumption that life insurance needs to replace every other retirement vehicle.
The better question is:
What financial risks and objectives does this client have, what resources are already available, and where might permanent life insurance appropriately fit?
How Does IUL Compare to Other Financial Products?
Agents frequently ask whether IUL is better than whole life, a 401(k), an annuity, or another financial product.
That’s usually the wrong question.
These products solve different problems. The appropriate solution depends on the client’s insurance need, objectives, available cash flow, liquidity requirements, time horizon, and overall financial situation.
| Option | Primary Purpose | Key Consideration |
|---|---|---|
| Indexed Universal Life | Permanent life insurance with cash value potential | Flexible but more complex and dependent on policy design and performance |
| Whole Life | Permanent life insurance with contractual guarantees | Generally more predictable with less premium flexibility |
| 401(k) | Employer-sponsored retirement savings | May include employer matching and direct investment exposure |
| Fixed Indexed Annuity | Accumulation and/or retirement income | Not life insurance and generally designed around accumulation or income |
| GIUL | Permanent life insurance emphasizing death benefit guarantees | Generally less focused on cash accumulation |
The appropriate solution depends on the client’s individual circumstances. These products should not be treated as direct substitutes based on a single feature.
How to Design an IUL Case
Good IUL case design starts with the client’s objective, not the carrier.
Don’t start by asking:
“Which IUL has the highest illustrated cash value?”
Start by asking:
“What is this client actually trying to accomplish?”
IUL Case Design Checklist
- Client age.
- State of residence.
- Health and underwriting information.
- Desired death benefit.
- Available premium.
- Planned funding duration.
- Existing life insurance.
- Cash value objectives.
- Potential future income or distribution objectives.
- Liquidity requirements.
- Existing retirement assets.
- Time horizon.
- Legacy objectives.
- Business planning needs.
- Estate planning considerations.
Death Benefit Objective
Start with the insurance need.
How much death benefit does the client need and why?
If the client’s only objective is inexpensive death benefit protection for a limited period, an IUL may not be the appropriate solution.
Cash Value Objective
If cash accumulation is part of the client’s objective, policy funding becomes extremely important.
An IUL designed around minimum premium and maximum death benefit can behave very differently from a policy designed around significant cash accumulation.
Client Age
Age matters because mortality costs are a significant component of life insurance pricing.
Don’t assume the product that illustrates well for a 35-year-old will necessarily be the appropriate design for a 60-year-old.
Funding Duration
Ask how long the client realistically expects to fund the policy.
- Ongoing annual premium.
- 10-year funding.
- 7-year funding.
- Shorter planned funding periods.
- Premium combined with a 1035 exchange.
How to Run and Review an IUL Illustration
One of the keys to selling IUL correctly is understanding the illustration.
An illustration demonstrates how a policy may perform under the assumptions permitted by the carrier and applicable illustration requirements.
It is not a promise of future non-guaranteed performance.
What to Review on an IUL Illustration
- Initial death benefit.
- Future death benefit.
- Death benefit option.
- Planned premium.
- Target premium.
- Premium duration.
- Cash value.
- Cash surrender value.
- Policy charges.
- Crediting assumptions.
- Loans and withdrawals.
- Guaranteed values.
- Non-guaranteed values.
Common IUL Illustration Solve Options
Solve to Endow
This solve is designed around a specified policy value or endowment objective at a future age according to the carrier’s illustration system.
Target Premium
A target-premium solve may calculate a death benefit or other policy values around the carrier’s target premium.
7-Pay / TAMRA
A 7-pay solve can help evaluate funding relative to Modified Endowment Contract rules.
Maximum Non-MEC
A maximum non-MEC design attempts to determine how much premium can be paid relative to the death benefit without causing the policy to become a MEC under the applicable testing assumptions.
Read our full max funded IUL guide.
Minimum Premium
A minimum-premium solve generally focuses on the premium required to support a particular policy design under the assumptions being illustrated.
Guideline Premium
Guideline premium relates to federal tax testing used to determine whether a contract qualifies as life insurance.
How to Use WinFlex for IUL Illustrations
WinFlex is commonly used by life insurance professionals to run carrier illustrations and compare products.
Depending on your upline relationship and carrier access, WinFlex can allow you to work with multiple carriers using a common illustration platform.
What Agents Can Do with WinFlex
- Create and store illustration cases.
- Access participating carriers.
- Compare different products.
- Adjust premium schedules.
- Model death benefit objectives.
- Model cash accumulation objectives.
- Adjust crediting strategies.
- Illustrate future distributions.
- Save case designs for future use.
Step 1: Log In to WinFlex

Step 2: Start a New Illustration

Step 3: Select the Carrier and Product
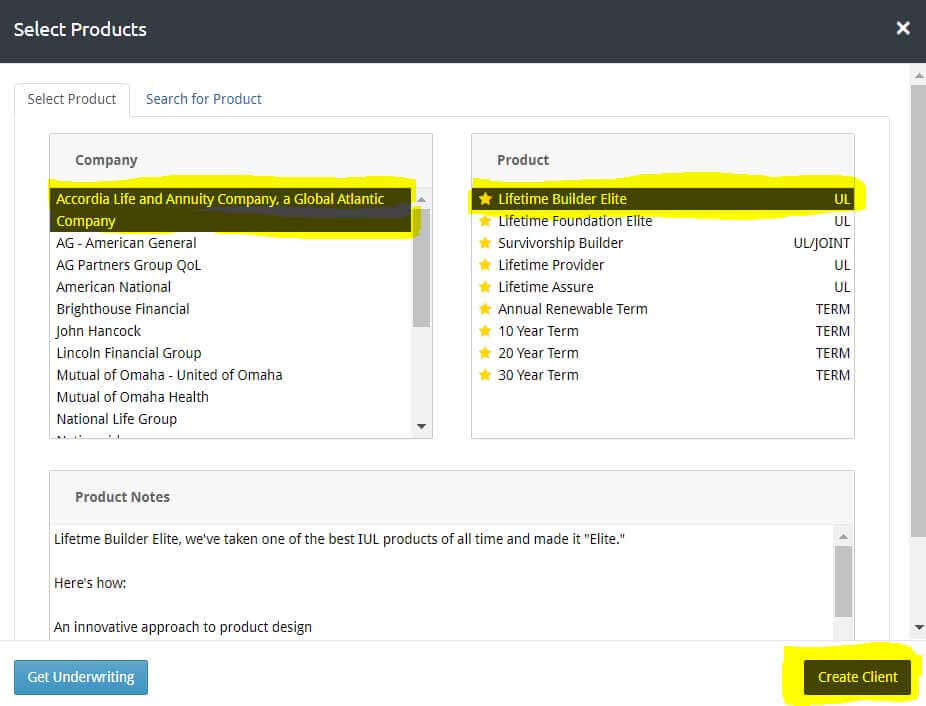
Step 4: Enter Client Information

Step 5: Design the Case

Once the basic information is entered, design the policy around the client’s needs.
At minimum, know:
- Desired face amount or premium.
- Planned premium duration.
- Whether a 1035 exchange is involved.
- Cash value objective.
- Whether future distributions will be illustrated.
- When distributions are expected to begin.
- Which death benefit option is appropriate.
- Which solve is being used and why.
How Do Clients Access IUL Cash Value?
One feature of permanent life insurance is the ability to access available policy value through withdrawals and policy loans.
Before discussing policy loans, understand how the carrier’s provisions affect:
- Cash value.
- Surrender value.
- Death benefit.
- Interest crediting.
- Policy charges.
- Policy lapse risk.
- Potential tax consequences.
Participating or Indexed Loans
Some policies allow values associated with a policy loan to continue receiving interest credits according to specified policy provisions.
Do not assume this creates a guaranteed positive spread between the loan rate and credited interest.
Fixed Loans
Some policies provide a fixed loan rate or loan structure. Review the contract to understand how borrowed values are treated.
Variable Loans
Some products use loan rates that can change over time according to the policy terms.
Withdrawals
A withdrawal permanently removes value from the policy and may reduce both cash value and death benefit.
How Do IUL Commissions Work?
Show me the money.
Agents ask all the time:
“How much money can an insurance agent make selling IUL?”
The answer depends on the carrier, product, contract level, target premium, advance structure, bonuses, and other compensation provisions.
But the first concept you need to understand is target premium.
What Is Target Premium?
Target premium is a carrier-defined premium amount commonly used to calculate first-year agent compensation.
Target premium is not necessarily the same as the client’s annual premium.
A client may pay more than the target premium into an IUL, particularly when the policy is designed for cash accumulation. That does not necessarily mean the agent receives the same first-year commission percentage on every dollar paid into the policy.
IUL Commission Example
Here’s a simple example of how target premium can affect an agent’s first-year IUL commission.
| Item | Amount | What It Means |
|---|---|---|
| Annual Premium | $1,500 | What the client plans to pay annually |
| Target Premium | $1,000 | Carrier-defined amount used for this commission example |
| Commission Rate | 85% | Agent’s assumed first-year compensation percentage |
| Gross First-Year Commission | $850 | $1,000 target premium × 85% |
This is a simplified example. Actual compensation depends on the carrier, product, contract, target premium, advance structure, bonuses, and applicable chargeback provisions.
What Happens to Premium Above Target?
This is where newer IUL agents sometimes get confused.
In the example above, the client is paying $1,500 annually, but the target premium is only $1,000. The agent’s 85% first-year commission is being calculated against the $1,000 target premium, not the entire $1,500 annual premium.
Compensation on premium paid above target varies by carrier and product. Some products may pay a smaller percentage on excess premium, while others may compensate excess premium differently.
Always review the actual carrier compensation schedule before calculating what you expect to earn on a case.
Commission Advances
Depending on the carrier and contract, agents may be able to receive an advance against expected first-year commissions.
Instead of waiting for each monthly premium payment before receiving the corresponding commission, a carrier may advance a portion of the expected first-year compensation after the policy is issued and placed in force.
That can improve agent cash flow, but an advance is not the same thing as guaranteed earned income.
Do IUL Agents Receive Renewal Commissions?
Renewal compensation varies by carrier, product, and contract.
Some products may provide renewal compensation after the first policy year, but the amount and duration can be substantially different from first-year compensation.
When evaluating an IUL contract, don’t look only at the headline first-year commission percentage. Review the entire compensation schedule.
Can IUL Agents Earn Production Bonuses?
Some carriers and distribution organizations offer additional compensation based on production.
Depending on the program, bonuses may be based on factors such as:
- Annualized target premium.
- Placed production.
- Persistency.
- Production tiers.
- Specific qualifying products.
- Overall carrier production.
Bonus programs can change, so agents should verify current requirements rather than assuming a historical bonus program still applies.
Getting Higher IUL Commission Levels
It never fails. Agents want top-level compensation.
That’s understandable, but compensation should be evaluated alongside the support required to actually write and place IUL business.
New IUL Agents
If you’re brand new to IUL and have no proven production, commission level should not be the only factor you use to choose an organization.
Good case design, underwriting, training, advanced market support, illustration assistance, and placement support can be considerably more valuable than a few additional compensation points.
If you’re learning the business, ask what happens when you actually have a case:
- Who helps determine which carrier may be appropriate?
- Who helps with preliminary underwriting?
- Who runs or reviews the illustration?
- Who helps structure the policy around the client’s objective?
- Who manages outstanding underwriting requirements?
- Who helps when the case becomes complicated?
A high contract level does not help much if you don’t have the support required to get business issued and placed.
Proven IUL Producers
If you’re a proven producer with documented IUL production, you may have more leverage when discussing compensation.
Be prepared to document your production and explain what you’re looking for from a new distribution relationship.
That conversation should include more than commission level. Consider:
- Carrier access.
- Case design support.
- Advanced underwriting.
- Case management.
- Advanced markets resources.
- Technology.
- Marketing support.
- Production bonuses.
- Service expectations.
What Is an IUL FMO, IMO, or BGA?
Independent life insurance agents commonly access carriers through wholesale distribution organizations that provide carrier contracts, case support, underwriting assistance, training, and other resources.
- FMO: Field Marketing Organization.
- IMO: Independent Marketing Organization.
- BGA: Brokerage General Agency.
- MGA: Managing General Agency.
- NMO: National Marketing Organization.
The terminology isn’t nearly as important as what the organization actually does for you.
With a product as complex as IUL, your distribution partner can play an important role in helping you design, underwrite, submit, and ultimately place business.
How to Evaluate an IUL FMO or BGA
Don’t evaluate an organization based only on commission level. Ask what happens after you actually bring them a case.
| Capability | Why It Matters | What to Ask |
|---|---|---|
| Case Design | IUL performance can be highly dependent on proper policy design. | Who actually designs and reviews my cases? |
| Underwriting | Carrier fit can materially affect underwriting outcomes and case placement. | Can you help me shop underwriting before submission? |
| Illustration Support | Illustrations can become complicated when designing around cash accumulation, distributions, 1035 exchanges, or other objectives. | Who can help me run and review illustrations? |
| Case Management | Cases can stall when underwriting requirements and follow-up are not managed effectively. | How are outstanding requirements tracked and communicated? |
| Advanced Markets | Business, estate, executive benefit, and larger cases may require additional expertise. | What advanced market resources are available? |
| Carrier Access | No single carrier or IUL product is appropriate for every case. | Which carriers can I access and compare? |
| Training | Getting contracted does not teach an agent how to properly design and sell IUL. | What ongoing product and sales training is available? |
| Technology | Illustration tools, case tracking, contracting systems, and other technology can make an agent more efficient. | What technology will I have access to? |
| Compensation | Contract level matters, but it should be evaluated alongside the support being provided. | What is my starting contract and what is required to earn higher levels? |
What Good IUL Case Support Should Look Like
Ideally, you should be able to bring your distribution partner a client situation before you’ve decided which carrier or product to use.
A strong case design conversation might start with:
- Client age and state.
- Health and underwriting history.
- Insurance need.
- Available premium.
- Funding duration.
- Cash accumulation objectives.
- Potential future distribution objectives.
- Existing life insurance.
- 1035 exchange opportunities.
- Business or estate planning considerations.
From there, the organization should be able to help evaluate underwriting, carrier fit, product design, illustration structure, and the process required to get the case placed.
How to Generate IUL Leads and Opportunities
IUL is a more complex sale than many traditional life insurance products.
That means the strongest opportunities don’t always come from someone filling out a form that says, “I want an IUL.”
Many prospects don’t know what an indexed universal life policy is, and even fewer understand whether one belongs in their financial plan.
Education and trust matter.
Instead of building your entire prospecting strategy around finding people already searching for IUL, build a system that consistently puts you in conversations where legitimate life insurance, retirement, business, estate, and legacy planning needs can be identified.
1. Become an IUL Expert
You don’t have to know every answer from memory, but you need to understand the fundamentals and know where to get help when a case becomes complex.
At minimum, you should be comfortable discussing:
- How indexed interest crediting works.
- Caps, floors, participation rates, and spreads.
- Policy charges and cost of insurance.
- Death benefit options.
- Cash value and surrender value.
- Policy loans and withdrawals.
- MEC rules and 7-pay testing.
- Guaranteed versus non-guaranteed values.
- Basic case design and illustration concepts.
The more confidently you can identify and explain legitimate planning issues, the easier it becomes to have productive conversations without turning every meeting into an IUL pitch.
2. Start With Your Existing Clients
Your existing book is often the easiest place to begin because these clients already know and trust you.
Instead of calling and asking whether they want to buy an IUL, offer a life insurance and financial protection review.
Look for changes such as:
- Income increases.
- Marriage or divorce.
- New children or grandchildren.
- New businesses or business growth.
- Changes in retirement goals.
- Existing policies that haven’t been reviewed in years.
- Term insurance approaching the end of its level term period.
- Changes in estate or legacy objectives.
3. Conduct Policy Reviews
A policy review gives you a legitimate reason to reconnect with existing clients and evaluate whether their current coverage still matches their needs.
You may discover that the client’s existing coverage is perfectly appropriate. You may also uncover outdated beneficiaries, insufficient death benefits, policies that are not performing as expected, changing financial objectives, or new planning needs.
Policy Review Language
I want to spend a few minutes reviewing what you currently have and what has changed since we last looked at your coverage.
Best case, we identify a gap or something that needs attention. Worst case, we confirm that everything is positioned exactly the way it should be.
Either way, we’ll know instead of guessing.
4. Ask for Referrals
If you’ve done good work for a client, ask whether they know someone else who could benefit from the same type of review.
Don’t make the referral request about IUL.
Make it about the problem you helped solve.
For example, if you helped a business owner review key person coverage and succession planning, ask whether they know another business owner who should be having the same conversation.
If you helped a family identify a life insurance gap, ask whether they know another family that hasn’t reviewed its coverage recently.
5. Build Centers of Influence
Develop relationships with professionals who already serve the types of clients you want to work with.
Potential centers of influence can include:
- Estate planning attorneys.
- CPAs and tax professionals.
- Employee benefits brokers.
- Property and casualty agents.
- Financial professionals.
- Business consultants.
- Bankers and commercial lenders.
- Business brokers.
- Other insurance professionals.
The objective isn’t simply to ask these professionals for leads. Learn what problems they solve, what types of clients they serve, and where life insurance expertise can complement their work.
6. Develop Strategic Partnerships
A center of influence can become much more valuable when the relationship develops into a repeatable strategic partnership.
Instead of occasionally exchanging referrals, look for situations where each professional brings a different area of expertise to the same client problem.
For example, a business owner planning for succession may need coordination between:
- An attorney.
- A CPA or tax professional.
- A business valuation professional.
- A financial professional.
- A life insurance agent.
Your role is not to replace those professionals. Your role is to understand where life insurance fits and bring insurance expertise into the planning process when appropriate.
7. Prospect Business Owners
Business owners can create multiple reasons to have a life insurance conversation because their insurance needs may extend beyond personal family protection.
Potential conversations can include:
- Buy-sell funding.
- Key person insurance.
- Business succession planning.
- Executive benefit strategies.
- Estate and legacy planning.
- Personal life insurance needs.
- Long-term business and personal financial planning.
Don’t lead with, “I sell IUL.”
Lead with the business problem and determine whether life insurance belongs in the solution.
8. Use Education as a Lead Generation Strategy
Because IUL can be difficult for consumers to understand, educational marketing can create opportunities without requiring you to lead with a product pitch.
Educational content might address questions such as:
- How does cash value life insurance work?
- What is indexed universal life insurance?
- How do life insurance policy loans work?
- What is a max funded IUL?
- What is a Modified Endowment Contract?
- How can life insurance be used in business succession planning?
- What is key person insurance?
- How does buy-sell life insurance work?
This content can be delivered through your website, email, educational events, client newsletters, social media, videos, or direct conversations.
The objective is to create informed conversations with people who have legitimate planning needs.
9. Build a Repeatable Follow-Up Process
Not every legitimate IUL opportunity will turn into an application during the first conversation.
Some prospects need additional education. Others may need to involve a spouse, business partner, attorney, CPA, or another advisor. Larger cases may also require preliminary underwriting or additional case design before a recommendation can be made.
Create a consistent process for tracking:
- New prospects.
- Discovery meetings.
- Policy reviews.
- Cases requiring illustrations.
- Cases requiring underwriting review.
- Applications submitted.
- Outstanding requirements.
- Policies issued.
- Policies placed.
- Future follow-up opportunities.
Who Is a Good Candidate for Indexed Universal Life Insurance?
One of the easiest mistakes to make with IUL is starting with the product and then trying to find someone who fits it.
I prefer to work the other direction.
Start with the client. Understand what they are trying to accomplish, what they already have in place, and where the gaps are. Then determine whether permanent life insurance belongs in the conversation and whether IUL is the right type of permanent insurance for the case.
Situations That May Create an IUL Opportunity
A client may be worth taking through a deeper IUL discovery process when several of the following are true:
- They have a legitimate need for permanent life insurance.
- They have enough predictable cash flow to fund the policy consistently.
- They have a long time horizon.
- They are interested in building cash value in addition to providing a death benefit.
- They want flexibility around premium or death benefit design.
- They are looking for additional ways to diversify long-term retirement or legacy planning.
- They own a business and have key person, buy-sell, succession, executive benefit, or estate planning needs.
- They already own permanent life insurance that has not been reviewed recently.
- Living benefit riders are relevant to their protection planning.
- They want to leave money to children, grandchildren, a charity, or other beneficiaries.
Who May Not Be a Good IUL Candidate?
IUL isn’t the answer to every financial problem, and saying no to a bad case is part of doing this business correctly.
Be careful when the client:
- Doesn’t have a legitimate life insurance need.
- Has unstable cash flow or is unlikely to maintain the planned funding.
- Needs most of the money to remain immediately liquid.
- Has a short time horizon.
- Is primarily looking for a short-term investment.
- Doesn’t understand that non-guaranteed policy values can perform differently from the illustration.
- Would have to ignore more basic financial priorities simply to fund the policy.
The goal isn’t to force IUL into the case. The goal is to identify the right cases and design them correctly.
How to Have an IUL Discovery Conversation
Before you run an illustration, ask questions.
A good discovery conversation should give you enough information to understand the client’s insurance need, financial priorities, existing resources, funding ability, and expectations.
IUL Discovery Questions
- What are you primarily trying to accomplish?
- How important is permanent death benefit protection to you?
- What life insurance do you currently own?
- When was the last time those policies were reviewed?
- What are you currently doing for retirement?
- Do you have an employer retirement plan and are you taking advantage of any available employer match?
- How much liquidity do you need to keep available?
- How much could you realistically commit to funding this strategy each year?
- How long do you expect to make those payments?
- Is leaving money to children, grandchildren, a charity, or another beneficiary important to you?
- Do you own a business or have an ownership interest in one?
- Are there buy-sell, key person, succession, or executive benefit issues we should consider?
- Are living benefits or access to policy value during your lifetime important to you?
You won’t ask every client every question in exactly this order. This isn’t an interrogation. It’s a framework to keep you from jumping into an illustration before you understand the case.
How to Explain IUL in Plain English
When a client asks what an IUL is, don’t make the explanation harder than it needs to be.
Indexed universal life is permanent life insurance. It provides a death benefit, and it can also build cash value over time. The policy isn’t invested directly in the stock market. Instead, the insurance company can credit interest based in part on the performance of an outside index, subject to the policy’s rules. The tradeoff is that these policies have charges, non-guaranteed elements, and funding requirements that we need to understand before deciding whether it makes sense for you.
That’s usually enough to start the conversation. You can explain caps, participation rates, loans, MEC rules, and illustration mechanics when they become relevant.
Where Can IUL Fit in Client Planning?
There is no single perfect IUL client. The product should be evaluated based on the client’s insurance need, objectives, available cash flow, time horizon, health, liquidity requirements, and ability to maintain the policy.
For agents, the opportunity is learning to recognize situations where permanent life insurance may deserve consideration. The planning need comes first. The product comes second.
Income Protection and Living Benefits
The primary purpose of life insurance is providing a death benefit, but some IUL products also offer riders that may allow a qualifying insured to accelerate a portion of the death benefit following certain qualifying events.
Depending on the carrier and rider, these provisions may address qualifying chronic illness, critical illness, terminal illness, or other specified events.
Definitions, eligibility requirements, benefit amounts, costs, and availability vary by carrier and state. Agents should understand exactly how the rider works before presenting living benefits as part of the policy’s value proposition.
What This Conversation Can Sound Like
A client may already have enough death benefit but hasn’t thought about what a serious illness could do to the family’s cash flow.
Instead of leading with a rider, ask the planning question:
If you had a serious health event and couldn’t work for an extended period, where would the money come from to keep everything running?
That question may uncover a need for disability income insurance, long-term care planning, emergency reserves, living benefits, or some combination of strategies. Your job is to identify the problem before deciding which product belongs in the solution.
Supplemental Retirement Planning
Some clients evaluate cash value life insurance as one component of a broader retirement strategy.
An appropriately designed IUL may provide permanent life insurance protection while also creating cash value that may be accessible through policy withdrawals and loans according to the policy’s provisions.
This does not make IUL a replacement for a 401(k), IRA, Roth account, or other retirement vehicle. The appropriate strategy depends on the client’s insurance need, existing assets, tax situation, liquidity requirements, time horizon, and overall financial plan.
Retirement Planning Conversation
I wouldn’t start this conversation by telling someone they need a “tax-free retirement plan.” Start by understanding what they already have.
Walk me through what you’re currently doing for retirement. What accounts are you funding, what benefits are available through work, and what do you feel is missing from the plan?
If the client has a permanent insurance need and sufficient long-term cash flow, cash value life insurance may become one of the strategies worth evaluating. If it doesn’t fit, don’t force it.
Legacy and Estate Planning
Permanent life insurance may be considered when a client wants to create liquidity or leave a death benefit for children, grandchildren, charities, businesses, or other beneficiaries.
Potential planning objectives may include:
- Creating a legacy for beneficiaries.
- Providing liquidity at death.
- Helping equalize inheritances among heirs.
- Supporting charitable objectives.
- Coordinating life insurance with a broader estate plan.
Estate planning cases can involve legal, tax, ownership, beneficiary, and trust considerations. Agents should coordinate with the client’s attorney, CPA, and other professional advisors when appropriate.
Business Owner Planning
Business owners can create a wide range of life insurance opportunities because their needs may extend beyond traditional family protection.
Permanent life insurance may be evaluated as part of buy-sell funding, key person protection, succession planning, executive benefit strategies, estate planning, and the owner’s personal insurance needs.
The next section of this guide takes a deeper look at how permanent life insurance can fit into business owner planning.
Existing Policy and 1035 Exchange Opportunities
Some IUL opportunities begin with a client who already owns permanent life insurance.
A policy review may uncover changes in the client’s needs, underperforming expectations, outdated policy design, changing death benefit objectives, or a contract that no longer aligns with the client’s current goals.
In appropriate situations, an agent may evaluate whether a tax-free exchange under Section 1035 should be considered as part of the client’s options.
A 1035 exchange should not be recommended simply because a newer product illustrates better. Agents should evaluate the existing policy’s guarantees, surrender charges, cost basis, existing loans, contestability considerations, new surrender periods, underwriting requirements, and other consequences of replacing coverage.
Children and Family Planning
Permanent life insurance may sometimes be considered as part of long-term family planning for children.
Potential objectives can include permanent death benefit protection, future insurability, long-term cash value accumulation, and legacy planning.
These cases should be evaluated as life insurance decisions rather than positioned as direct replacements for traditional education or investment accounts.
Family Planning Conversation
Parents and grandparents don’t usually wake up searching for “IUL for children.” They think about protecting their family, helping the next generation, college, future insurability, and leaving something behind.
A simple way to open the conversation is:
You’ve done a lot to protect your own financial plan. Have you ever looked at what you want to put in place for the kids or grandkids long term?
From there, learn what they actually mean. The answer may lead to life insurance, education planning, gifting, estate planning, or something else entirely.
How Business Owners Can Use Permanent Life Insurance
Business owners can create some of the most interesting life insurance planning opportunities because the need for coverage may extend beyond personal family protection.
Buy-Sell Funding
A buy-sell agreement establishes what happens to an ownership interest following specified triggering events.
Life insurance is commonly evaluated as one potential funding mechanism when the death of an owner is a triggering event.
The amount and ownership structure of the coverage should coordinate with the actual buy-sell agreement and the client’s legal and tax advisors.
Key Person Insurance
Key person insurance solves a different problem.
Instead of funding the purchase of an owner’s equity, key person coverage is generally designed to help protect a business from the economic loss associated with the death of an important owner, executive, salesperson, or employee.
- Replace lost revenue.
- Recruit a replacement.
- Train a replacement.
- Provide working capital.
- Meet obligations during a transition.
Business Cash Reserves
Some business owners maintain substantial cash reserves and may ask whether permanent life insurance could play a role in their overall business and insurance strategy.
This requires considerably more analysis than simply comparing a money market rate to an illustrated IUL rate.
Consider:
- Why the business maintains the cash.
- How much liquidity must remain immediately available.
- The owner’s actual insurance need.
- Surrender charges.
- Early cash value provisions.
- Policy ownership.
- Tax and accounting treatment.
- Loan provisions.
- Business succession objectives.
- The impact of lower-than-illustrated performance.
Business Owner Prospecting Language
Hey [Name],
I’m reaching out because I’ve been doing more work with business owners around life insurance, succession planning, key person risk, and how businesses are positioning long-term cash.
It made me think of you.
I don’t know whether there is anything we need to address, but I’d like to spend 15 minutes learning how you currently handle those areas and see if there are any gaps worth reviewing.
Would Tuesday or Thursday work for a short call?
IUL Agent Frequently Asked Questions
What is indexed universal life insurance?
Indexed universal life is a form of permanent life insurance that provides a death benefit and cash value. Certain policy accounts can receive interest credits determined using an external index and the crediting provisions of the insurance contract.
Is money in an IUL invested directly in the stock market?
No. An indexed crediting strategy may reference the performance of an external market index, but the policyholder is not directly purchasing shares of that index through the IUL policy.
Can an IUL lose money?
Policy cash value can decline. A 0% indexed floor can prevent a negative index result from directly creating a negative indexed interest credit under that strategy, but policy charges, loans, withdrawals, and other activity can still reduce policy value.
How much commission do agents make selling IUL?
IUL compensation varies by carrier, product, contract level, target premium, distribution relationship, production, and applicable bonus programs. Always review the actual carrier compensation schedule.
What is target premium on an IUL?
Target premium is a carrier-defined premium amount commonly used when calculating agent compensation. It is not necessarily the amount a client should pay to properly fund the policy.
What is a max funded IUL?
A max funded IUL generally refers to a policy designed to accept significant premium relative to the death benefit while remaining within applicable life insurance tax rules and avoiding MEC status when non-MEC treatment is part of the client’s objective.
What is a MEC?
A Modified Endowment Contract is a life insurance contract that fails the applicable 7-pay test. MEC status changes the tax treatment of policy distributions.
How do IUL policy loans work?
Policy loans allow the policyholder to borrow against available policy value according to the contract. The loan accrues interest and can affect cash value, surrender value, death benefit, and policy performance.
What is the best IUL company?
There is no single IUL carrier that is best for every client. Carrier selection can depend on age, health, underwriting, death benefit objectives, cash accumulation objectives, funding pattern, loan provisions, living benefits, guarantees, and state availability.
What is the best way to generate IUL leads?
There is no single source that works for every agent. Existing client reviews, referrals, centers of influence, business owners, educational marketing, professional relationships, and strategic partnerships can all create legitimate IUL opportunities.
Is IUL better than whole life?
Not universally. Whole life and IUL use different approaches to premiums, guarantees, cash accumulation, flexibility, and non-guaranteed policy performance. The appropriate product depends on the client’s objectives.
Does an independent agent need an IUL FMO or BGA?
Many independent agents access carriers through BGAs, IMOs, FMOs, MGAs, or similar distribution organizations. Evaluate case design, underwriting, carrier access, advanced markets support, case management, training, technology, and compensation.
Build an IUL Practice, Not Just an IUL Pitch
The agents who build sustainable IUL businesses aren’t simply the agents with the highest contracts or the prettiest illustrations.
They understand the product, ask better questions, design policies around actual client needs, set realistic expectations, and surround themselves with people who can help handle complex cases correctly.
What Your IUL Support System Should Provide
- Case design.
- Illustration support.
- Underwriting.
- Case management.
- Carrier selection.
- Advanced markets support.
- Ongoing training.
- Agent technology.
- Lead generation and marketing resources.
- Long-term policy service.
Picking the right partner can make a major difference in how quickly you learn and how effectively you serve your clients.
We believe Redbird can be that partner, but you should evaluate us using the same standards outlined in this guide.
Ready to Build Your IUL Practice?
Redbird helps independent insurance agents with IUL contracting, case design, illustrations, underwriting, training, and sales support.